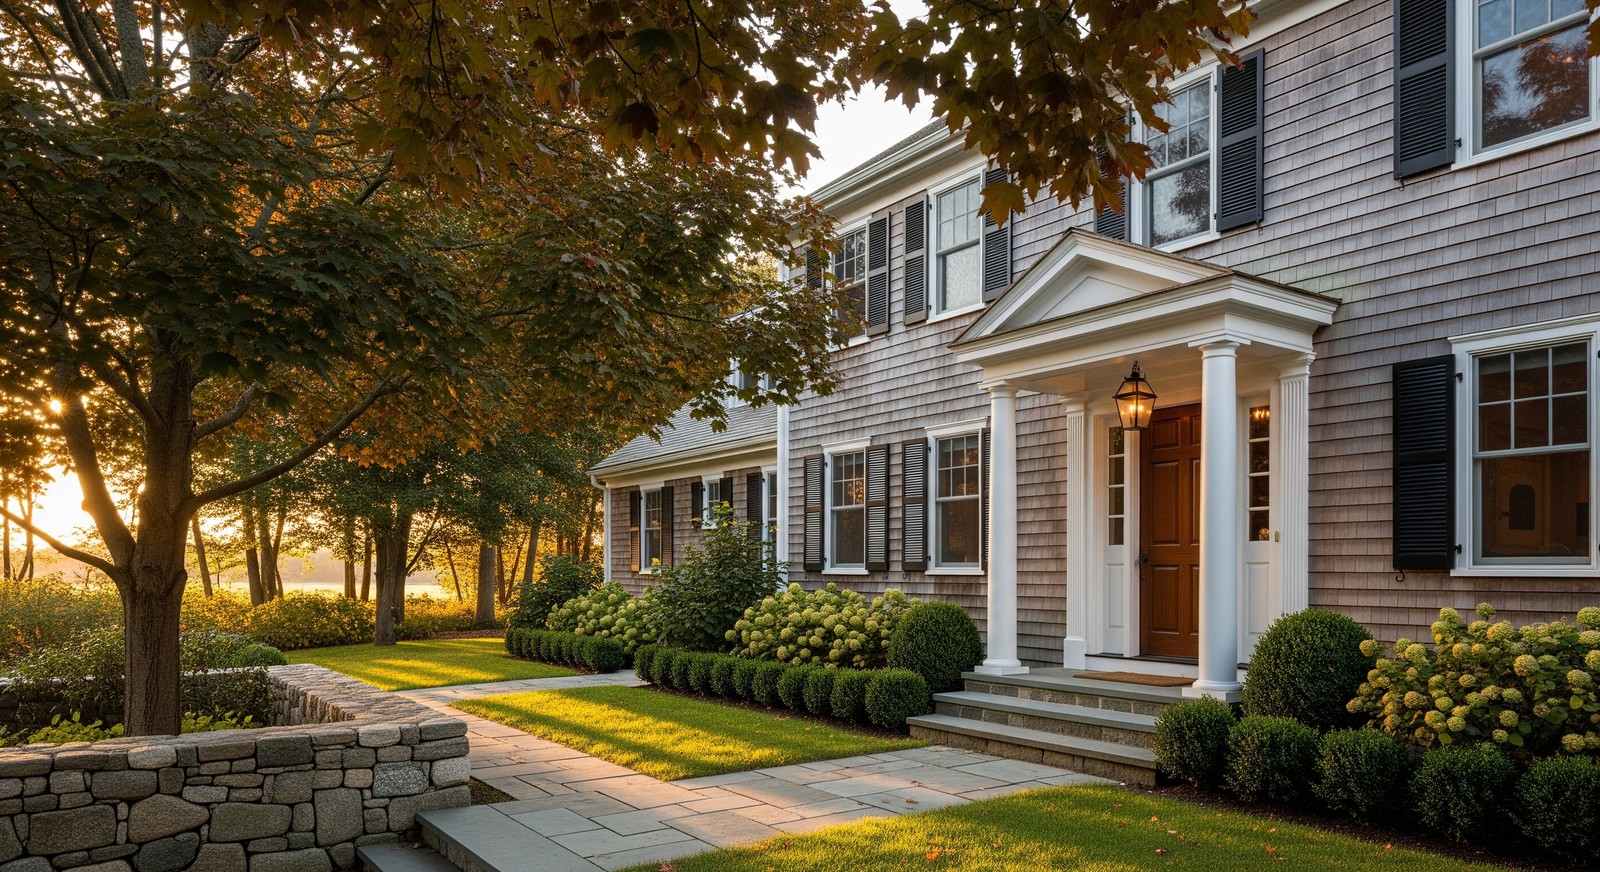
Thinking about utilizing your home equity to stay in your Hanover home longer? A reverse mortgage—specifically the FHA-insured Home Equity Conversion Mortgage (HECM)—can be a powerful financial tool for seniors on the South Shore. However, it is not a universal solution. This guide provides clear, authoritative answers regarding program mechanics, local obligations in Plymouth County, and the steps you must take before making a decision.
- Key Takeaways:
- Borrowers must be at least 62 years old and use the home as a primary residence.
- HECMs are non-recourse loans, meaning you will never owe more than the home's value.
- Ongoing responsibilities include property taxes, homeowners insurance, and basic maintenance.
- Mandatory HUD counseling is required to ensure homeowners understand all alternatives.
Understanding Reverse Mortgage Basics (HECM)
A reverse mortgage allows homeowners to convert a portion of their home equity into cash. With a HECM, you retain the title to your property. You can receive funds through a line of credit, monthly installments, a lump sum, or a customized combination. The loan typically becomes due when the last surviving borrower or eligible non-borrowing spouse passes away, sells the home, or moves out permanently.
According to the Consumer Financial Protection Bureau (CFPB), these are non-recourse loans. This core consumer protection ensures that if the home sells for less than the loan balance, FHA insurance covers the difference. To learn more about program mechanics, you can review the official HUD HECM program page.
Determining How Much Equity You Can Access
The amount of funding available—known as the principal limit—is not the full value of the home. Instead, it is calculated based on three specific factors:
- The age of the youngest borrower (older borrowers typically qualify for more).
- Prevailing interest rates.
- The lesser of the home’s appraised value or the current FHA lending limit.
If you currently have a traditional mortgage on your Hanover property, the HECM proceeds must first be used to pay off that balance in full at closing. Any remaining funds are then available for your use.
Mandatory Counseling and Financial Assessment
Before moving forward, Massachusetts residents must complete a session with a HUD-approved housing counselor. This session covers costs, tax implications, and alternatives like a Home Equity Line of Credit (HELOC) or rightsizing to a smaller home in nearby Scituate or Norwell.
Lenders also conduct a financial assessment to ensure you can sustain the "triple threat" of homeownership: property taxes, insurance, and maintenance. If your credit history or income suggests a risk, the lender may require a Life Expectancy Set-Aside (LESA), which earmarks a portion of your loan proceeds specifically to pay future property charges.
Your Ongoing Obligations in Hanover, MA
Maintaining a reverse mortgage requires diligent attention to local property requirements. Failure to meet these obligations can result in the loan being called due.
Real Estate Taxes and Exemptions
You remain responsible for your local tax bill. Homeowners should consult the Hanover Assessor’s Office to discuss current rates and potential senior exemptions. Additionally, the Massachusetts Senior Circuit Breaker tax credit may provide financial relief for eligible residents based on their income and tax payments.
Insurance and Flood Risk Management
Continuous homeowners insurance is mandatory. Because portions of the South Shore are susceptible to coastal or inland flooding, your lender will verify your status via the FEMA Flood Map Service Center. If your property is in a Special Flood Hazard Area, flood insurance will be required.
Condo and HOA Compliance
If you reside in a managed community or condominium, you must remain current on all HOA dues. For HECM eligibility, the condo association itself must often be FHA-approved. Before applying, gather your association’s budget and reserve reports to ensure the project meets federal standards.
Hanover Due Diligence Checklist
- Confirm all borrowers are at least 62 and the home is a primary residence.
- Obtain a professional market valuation to understand your current equity position.
- Locate an approved counselor through the HUD locator.
- Search your title and check for existing liens at the Plymouth County Registry of Deeds.
- Compare written estimates from at least two FHA-approved lenders.
- Consult an elder-law attorney regarding Medicaid planning and estate goals.
Costs and Closing Expenses
HECMs carry specific costs that are often rolled into the loan balance. These include the FHA Mortgage Insurance Premium (MIP), lender origination fees (capped by HUD), and standard third-party closing costs such as appraisals and title searches. Always request a "Net Proceeds" estimate to see exactly how much cash will be available to you after these expenses.
Deciding: Age in Place or Rightsize?
A reverse mortgage is an excellent tool for those who love their Hanover neighborhood and wish to stay. However, if your home requires excessive maintenance or the layout is no longer safe for aging, HECM for Purchase might be an alternative. This allows you to buy a new, more accessible home (perhaps a single-level home in a neighboring South Shore town) using a reverse mortgage to cover a portion of the purchase price, eliminating monthly mortgage payments for as long as you live there.
Standardized Planning Resources
- Hanover Council on Aging: Provides information on local senior services and transportation.
- Massachusetts Division of Banks: Use this to verify lender licensing and consumer protection alerts.
- Plymouth County Registry of Deeds: Useful for reviewing your property's legal history.
Frequently Asked Questions
What is a reverse mortgage and who qualifies in Hanover?
A reverse mortgage is an FHA-insured loan (HECM) that allows homeowners 62 and older to access their home equity without making monthly mortgage payments. To qualify, you must own the home outright or have significant equity, use it as your primary residence, and complete a mandatory HUD counseling session.
Do I still have to pay property taxes with a reverse mortgage?
Yes, you are fully responsible for property taxes, homeowners insurance, and upkeep. In Hanover, you should coordinate with the Assessor’s Office to ensure your taxes are paid on time, as failure to do so can cause the loan to default and the balance to become due immediately.
What happens to the home when the borrower passes away?
When the last borrower leaves the home, the loan balance becomes due. Heirs typically have the option to sell the home to repay the debt, keep any remaining equity, or purchase the home for 95% of its appraised value; because it is a non-recourse loan, heirs are never personally liable for a balance that exceeds the home's value.
Can I use a reverse mortgage to buy a new home in Massachusetts?
Yes, the HECM for Purchase program allows you to buy a new primary residence by providing a down payment from your own funds (such as proceeds from a previous home sale). The reverse mortgage then covers the remainder of the purchase price, allowing you to move into a more suitable home without a monthly mortgage bill.
For personalized guidance, please contact Juli Ford at 617-733-1124. Juli is a Reverse Mortgage Specialist and Mortgage Loan Originator through Texana Bank, licensed in all 50 states (NMLS ID: 2728620).
Explore more tips & guides
Explore Resources & Guides: Planning a day out with three generations in tow? That's my specialty. Grab the free Multi-Generational Living Guide for support navigating life together, at every stage. Plus more guides, checklists, and tools for your next move. juliford.com/multi-gen.
Workshops & Events: Join live workshops and events on real estate, multi-generational living, and agent growth. juliford.com/events.
Book a Strategy Session: Let's map out a plan that fits your family and your timeline. juliford.com/consulting.
About the Author
Juli FordFounder of Home After 50 · CSA · Licensed Real Estate Broker
Juli Ford is the founder of Home After 50, a nationally recognized multigenerational living expert, real estate broker, and Certified Senior Advisor® helping women and families reimagine home and life in the next chapter, together.
As featured in The New York Times, Newsweek, Business Insider and Fox & Friends.
Read More Blogs
Related Articles
Home After 50 | Multi-Gen Living
5 Money Talks Every Multigenerational Home Should Have Before the Holidays (Ranked Easiest to Hardest)
Home After 50 | Multi-Gen Living
Will Your Home Equity Pay For In-Home Care? What a New Study Found
Multigenerational Homes